ServicesFinal Expense Insurance
Final Expense Insurance in Walnut Creek
Final expense insurance is a small whole life policy built to pay funeral costs, medical bills and the loose ends that land on family. We start by reading the coverage you already have, then size a policy only for the gap that remains.
What Final Expense Coverage Does
A final expense policy is permanent whole life insurance with a modest face amount. The premium is fixed for life, the coverage does not expire at a certain age, and the policy builds a small cash value over time. When you pass, your beneficiary receives the benefit directly and can use it for the service, burial or cremation, an outstanding hospital balance or a final utility bill.
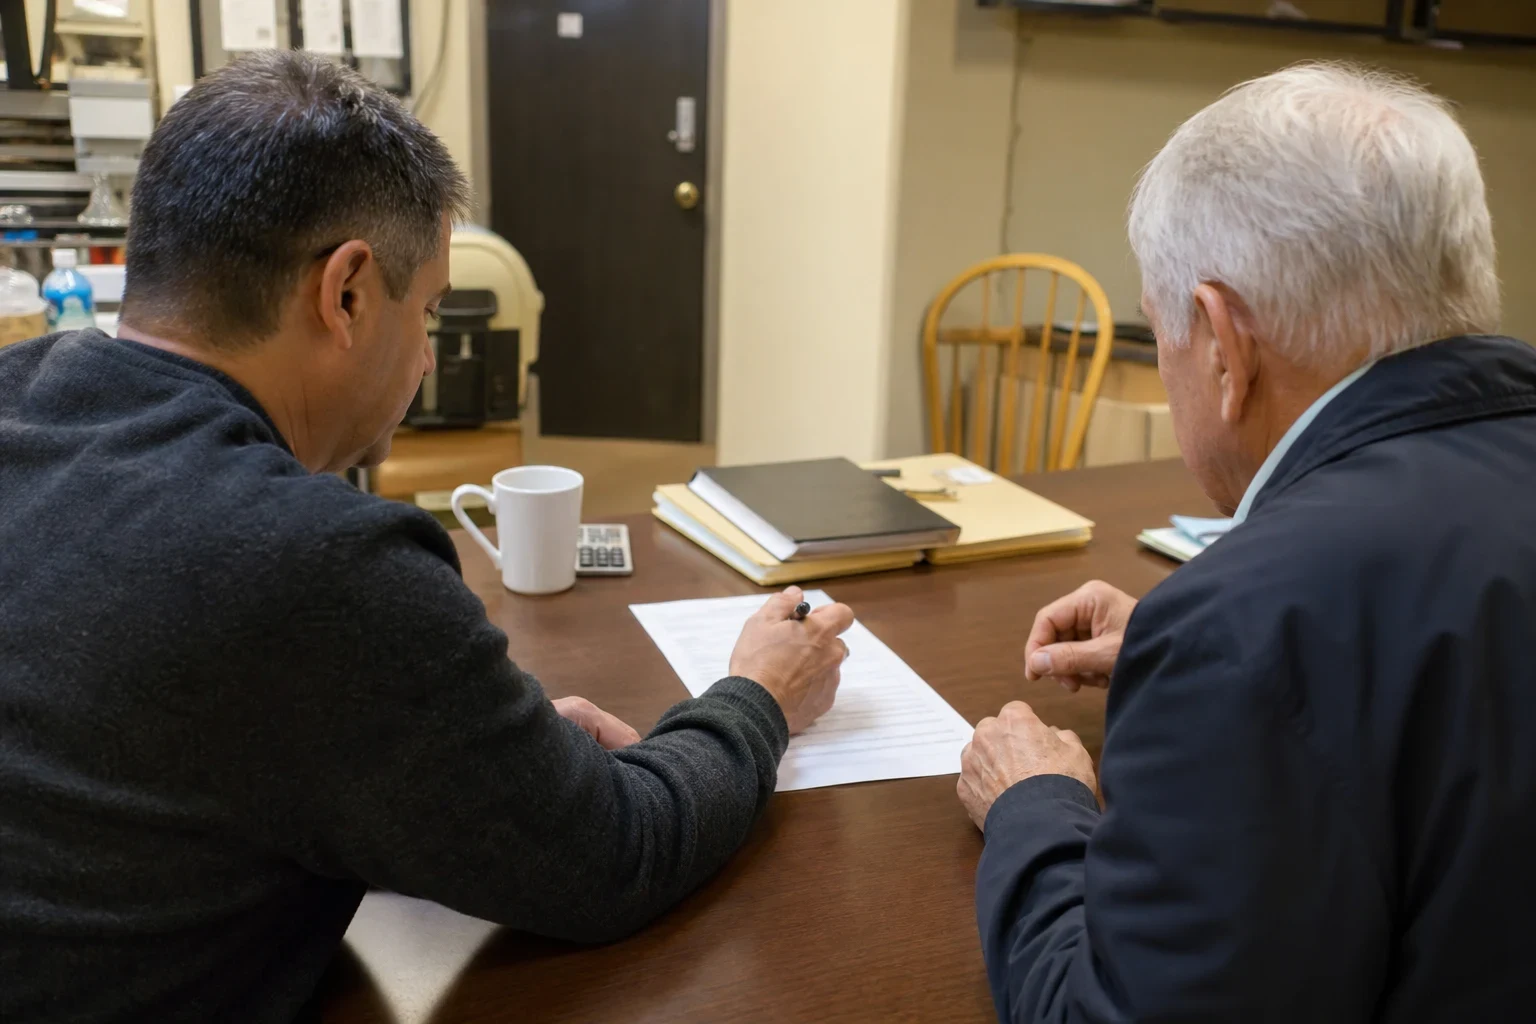
Many clients already own something that does part of this job: an old whole life policy, group coverage through a former employer, a paid-up policy a parent bought decades ago. Keeping and adjusting what works is often cheaper than starting over, because older policies were priced at a younger age. When an existing policy has lapsed, carries a loan that is eating the cash value, or names a beneficiary who is no longer right, we say so plainly and explain whether fixing it or replacing it makes more sense.
What Our Review and Policy Work Includes
- Existing policy read-through
- We go through each policy you bring, line by line. We note the face amount, premium, cash value, any outstanding loans and whether the coverage is term or permanent. You leave knowing exactly what you own.
- Gap sizing
- We add up the costs your family would actually face and subtract what current coverage already pays. The new policy, if you need one, covers only the difference.
- Underwriting type matched to your health
- Simplified issue policies ask a short set of health questions with no medical exam. Guaranteed issue policies ask none but usually carry a graded benefit for the first two years. We explain which one your answers point to and why.
- Beneficiary and ownership setup
- We help you name a primary and contingent beneficiary and confirm the policy owner is correct. A missing contingent beneficiary is one of the most common reasons a benefit gets delayed.
- Annual check-in
- Costs and family situations change. We look at the policy again with you each year so the beneficiary and amount still fit.
Signs It Is Time to Look at Final Expense Coverage
Your term policy is ending
Term life expires at the end of its term, often in your sixties or seventies. Renewing at that age can cost far more than a small permanent policy.
Group coverage stopped at retirement
Employer life insurance usually ends or shrinks sharply when you leave the job. Many people do not notice until they read the retirement paperwork.
You are not sure what an old policy is worth
A policy bought years ago may still be in force, partly paid up or quietly lapsed. Finding out takes one review, and it may mean you need less new coverage than you think.
Your health has changed
A new diagnosis can narrow your underwriting options. Locking in a simplified issue policy while you still qualify keeps the full benefit available from day one.
Family would have to cover the bills
If your children or spouse would pay for the service out of savings, a policy sized to those costs takes that weight off them.
What Sets the Premium
A final expense premium is fixed at issue and stays level for life, so your starting price is the price you keep. Five things determine it, and we cover each one before you apply so nothing in the quote catches you off guard.
Your age when issued
Every added year raises the rate, because the carrier expects to collect premiums for fewer years. Applying earlier locks in a lower level premium for good.
Benefit amount
A bigger benefit costs more. Covering only what your current coverage leaves unpaid keeps this figure realistic.
Your health answers
Heart disease, diabetes or a recent hospital stay can shift you from simplified issue to guaranteed issue, which costs more per dollar of coverage and comes with a graded period.
Tobacco
Tobacco users, smokers included, land in a higher rate class. Some carriers check the past twelve months, while others look back further.
How long you pay
Some policies are paid for life and others over a fixed number of years. A shorter schedule means bigger payments that end earlier.
How a Final Expense Appointment Works
- 1
A phone conversation first
You tell us your age, rough health picture and what policies you already hold. We tell you what to have on hand for the review.
- 2
Policy review at your business or by phone
We read your existing statements with you and mark what each one pays. If an old policy can be reinstated or its beneficiary updated, we start there.
- 3
Quote for the remaining gap
We show you quotes for the amount still uncovered, with the premium, underwriting type and any waiting period written out. You compare them without pressure.
- 4
Application and delivery
Simplified issue applications take a short set of yes-or-no health questions. Once the carrier approves it, we walk through the delivered policy with you and confirm the beneficiary details.
Common Final Expense Questions
What separates final expense from standard whole life?
It is the same kind of permanent coverage, with a smaller face amount and lighter underwriting. Most of these policies need no medical exam, so they are issued faster and are easier to get later in life.
How does a graded benefit work?
With guaranteed issue, a death from natural causes during the first two years usually returns the premiums paid plus interest rather than the full benefit. Accidental death is generally paid in full from day one. Once the graded period ends, the full benefit applies.
Should I drop my old policy and get a new one?
Not until we review it. An older policy was priced when you were younger and may have built cash value. If it carries a big loan, is at risk of lapsing or covers too little, we explain whether to adjust it, add to it or replace it.
Can my beneficiary spend the money however they choose?
Yes. The benefit is paid to the person you name rather than the funeral home, and they can use it for the service, medical balances or any other bills.
How quickly is a policy approved?
Simplified issue decisions often come fast once the application is submitted, though each carrier sets its own pace. Guaranteed issue skips the health review, so approval is largely paperwork. Before you apply, we tell you what to expect from the carrier you choose.
Find Out What You Already Have
Bring your old policy statements, even the ones in a drawer. We will read them with you, show what they pay and size any new coverage to the gap, for clients in Walnut Creek, Concord, Pleasant Hill and nearby.